


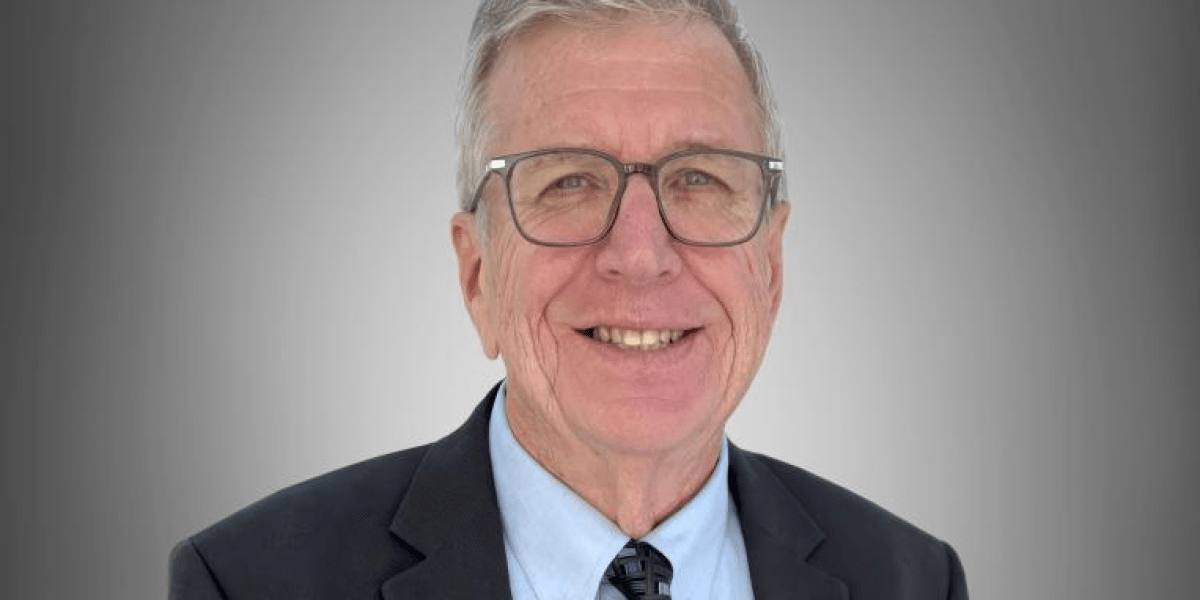



Stacey Moser, Executive Vice President, Chief Customer Officer, Verra Mobility.
Fleet management is experiencing one of its most significant transformations since GPS tracking. The U.S. fleet management market, valued at over $12 billion in 2024, is projected to reach nearly $29 billion by 2032, driven by a fundamental shift toward embedded connectivity that’s revolutionizing how companies manage assets, control costs and optimize performance.
With approximately 2.8 million commercial vehicles registered in the U.S. in 2024 and business fleets representing a large share of vehicles on U.S. roads, this shift affects far more businesses than traditional fleet operators may realize.
From Add-On Devices To Mobile Data Centers
Today’s fleet managers often juggle fragmented solutions: GPS dongles, fuel management cards, driver monitoring hardware and multiple toll devices. It’s reminiscent of TVs once needing separate cable boxes, DVD players and gaming consoles, each wired in individually.
Many vehicles manufactured after 2019 are fundamentally different. They’re mobile data centers with multiple processors, substantial memory and cellular connectivity. These vehicles generate tremendous data over cellular networks, offering unprecedented operational visibility.
Dongles read data through the OBD-II port, originally designed for emissions diagnostics, and surface only a limited subset of what the vehicle generates. Direct manufacturer partnerships access deeper data streams from factory-installed hardware, providing richer operational information and enabling new management capabilities.
How Real-Time Operations Can Transform Business Costs
Embedded connectivity is helping fleet operators shift from reactive management toward proactive, real-time decision-making. Consider toll expenses—typically one of the highest operational costs for vehicle fleets, after insurance and fuel. Traditional approaches require reviewing transactions after the fact, basically conducting compliance audits to ensure drivers followed cost-effective routes.
Connected vehicles can alert drivers in real time when they approach expensive toll locations like the George Washington Bridge, prompting a route change. They can also flag fraud automatically when a transponder’s location doesn’t match its assigned vehicle, signaling the device has been moved.
This dynamic is already playing out beyond tolling operators. In September 2025, Mastercard, Volvo Cars and the North Carolina Turnpike Authority launched a pilot program that lets drivers pay tolls directly from the vehicle, using GPS positioning and tokenized payment credentials in place of a transponder.
More advanced capabilities, still maturing industrywide, include automated dispute resolution: When infrastructure errors charge a light vehicle the toll price of a large truck, connected vehicle data can flag the discrepancy and initiate a correction.
Driver monitoring can also grow more sophisticated with comprehensive sensor data. While traditional systems flag only major deviations from normal driving, connected vehicles can catch subtler ones, enabling earlier coaching and preventing costly incidents.
Maintenance is shifting from scheduled intervals toward predictive models based on actual performance data. For example, this includes vehicles that can automatically schedule service appointments and pre-authorize payments, though how far fleets have operationalized this varies.
Ford Pro’s telematics platform shows this in practice: Embedded modems relay vehicle health data into Ford Pro Intelligence, which can surface a maintenance alert in near real time so fleet managers can schedule service before a component fails, an approach the company has described as a “zero-downtime” service model.
Integration Challenges And Solutions
Unlike standardized dongle interfaces, each manufacturer today uses proprietary operating systems and data formats, with little standardization on the back end.
Data ownership remains a complex issue. Companies must negotiate with OEMs or third parties to determine who controls vehicle data and access permissions. Some manufacturers run their own data groups; others work through third-party aggregators, creating inconsistent landscapes for integrated solutions.
New Revenue Opportunities
Once standards develop, connected fleets can enable entirely new service categories: automated payment for gas stations, EV charging, parking and even drive-through purchases, without corporate credit cards or expense reports.
The rental car industry exemplifies this transformation. Bypass-the-counter initiatives have proven popular—J.D. Power’s 2025 rental car study found bypass customers report meaningfully higher satisfaction than those who stop at the counter—but they’ve also created a revenue trade-off, since services once sold at the counter, from insurance to fuel packages, lost their natural point of introduction. Connected vehicles can instead surface those options through infotainment systems at the moment customers need them, improving convenience without adding friction.
Business Applications Beyond Transportation
I’ve seen early adoption cluster in sectors where vehicle utilization is high and margins are tight, such as last-mile delivery, rental car and utility field services. Adoption has been slower in industries with smaller, mixed-brand fleets, such as real estate, home services and specialty contracting, where integrating multiple OEM platforms often outweighs near-term gains.
Implementation challenges remain across segments. Smaller operators, in particular, face a real obstacle: The business case can be compelling in theory, but the cost and effort of moving off familiar dongle-based systems is significant.
Commercial fleets are often an early proving ground for connected vehicle capabilities, since businesses can evaluate these technologies through measurable outcomes like reduced costs and improved utilization. Consumer adoption tends to follow a different path, growing as connected services demonstrate clear value in everyday use. Fleet deployments often help validate technologies that later expand into personal vehicles.
Future Implications
The transformation remains in early stages. Industry associations like COVESA are promoting standards to simplify integration, but adoption today is shaped by practical factors: fleet size and vehicle mix, OEM data access terms, existing telematics investments and internal capacity to manage integration.
Organizations are taking different paths as a result. Some are consolidating fleets around specific OEM platforms to unlock deeper data access. Others maintain hybrid setups—dongles on older vehicles, embedded connectivity on newer ones—while waiting for standards to mature.
Connected fleets represent one meaningful direction the market is moving, alongside continued investment in traditional telematics and emerging aftermarket alternatives. For business leaders, the real question is less about a single right answer and more about how complexity, data access and cost trade off for their specific operations.
Forbes Technology Council is an invitation-only community for world-class CIOs, CTOs and technology executives. Do I qualify?


